
Finding an orchard for sale in Bourgogne-Franche-Comté takes patience: the region is not one of France's big shipping basins, yet it keeps well-known cherry country in Franche-Comté, apple and pear blocks turned into juice and fruit spirits, and blackcurrant plantings inherited from the Burgundian tradition. Growers handing over, rural agencies and notaries place their offers here: species planted, age of the fruit trees, harvesting equipment and, where there is one, the processing workshop. Every one of them also appears in our national selection of orchards for sale.
To that we add a few market bearings: land prices across the eight departments, the areas where fruit-growing holdings come up most often, how to read an ageing orchard and the formalities that come with taking over a farm. If your plan is to set up, our white paper « Créer une exploitation agricole » (in French) describes each stage, from funding to the agricultural qualification.
Land forms the base of the value of an orchard. DVF, the property sales database published by the French tax administration (vineyards excluded), records farmland changing hands in Bourgogne-Franche-Comté at a median of €2,773/ha in 2025, average €2,907/ha, over 1,303 sales. Four sales in five fall between €1,813 and €4,185/ha; the national benchmark is €5,307/ha.
The SAFER benchmark completes the picture: €2,740/ha in 2025 for vacant land and pasture (-6.2% in a year, -8.1% in ten), against a national average of €6,460/ha, with let land trading some 17% below that.
With this kind of property, the land itself says little about the price. What counts is the orchard and its future: species and varieties, average age of the rows, share of blocks due for replanting, quality of the training and pruning, access to water, and whatever is in place against spring frost. Then come the shed, the cold store, the harvesting equipment, the still or the juice workshop, and the customer base already built up. Set the whole against our land price observatory and test your takeover plan with our financial calculators.
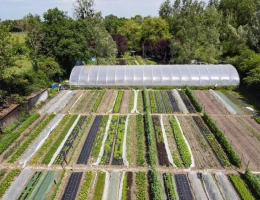
Two worlds sit side by side here. On one hand, older blocks of standard or half-standard apple, pear, plum and cherry trees, managed extensively and destined for juice, jam or distilling; on the other, densely planted, wire-trained orchards on dwarfing rootstock with a replanting schedule that has been kept up. The first visit is there to settle which you are looking at: a commercial orchard, or a stock of trees to bring back into condition. Look at the evenness of the rows, the share of dead or declining trees, the height of the trunks, the vigour, the framework branches and the date of the most recent plantings.
Protection against weather risk then makes the difference. Spring frost is the main threat here, above all on cherries and apricots, and few holdings are equipped with frost fans or sprinklers; hail nets remain a minority. That makes the aspect of each block, the slope and the air drainage decisive. Irrigation is less widespread than in the south of France, but access to water is a solid argument on young plantings. Where the sale includes a house, outbuildings and land, insist on an item-by-item breakdown of the asking price.
Haute-Saône (70) holds the best-known centre, around Fougerolles, where cherry blocks have long supplied a kirsch industry recognised by an appellation, with small distilleries and well-established direct sale. Doubs (25) continues that tradition in the Loue valley, near Mouthier-Haute-Pierre, where hillside cherries and fruit spirits have a place of their own; the blocks are small, fragmented and often awkward to reach. Territoire de Belfort (90), the smallest of the eight, mainly has valley orchards of apples and plums, geared to the markets of the town and the neighbouring urban area.
Jura (39) offers hillside orchards between the Revermont and the first plateaux, often paired with juice or spirit production, on land made dearer wherever vines and tourism compete for the best aspects. Côte-d'Or (21) remains the blackcurrant department, grown in the Hautes-Côtes and bought up by the Dijon liqueur houses, with a few hillside orchards alongside; approaching Dijon and the vineyard, land is among the most expensive in the region. Saône-et-Loire (71) completes the picture with orchards and soft fruit plantings in the Saône valley and around Chalon, sold through short supply chains and on urban markets.
Yonne (89), the closest to the Paris region, keeps cherry blocks and hillside orchards in the Auxerrois and the Tonnerrois, with pick-your-own and direct sale driven by Parisian custom; land rises sharply where the vineyards begin. Nièvre (58), dominated by Charolais cattle and woodland, offers the most moderate entry prices and, above all, farmsteads where part or all of the orchard remains to be replanted. In short, supply is widest in the east of the region, prices are tightest around the vineyards and the towns, and the openings for creating something new lie in the centre and the west.
Few holdings here live on selling fresh fruit alone. Processing is the rule: a pasteurised juice workshop, a jam kitchen, a drying room, or a still for kirsch and fruit spirits, with the customs obligations that alcohol production carries. Examine the health approval of the premises, the state of the press and the tanks, the capacity of the cold store, any grading equipment and the stock of bottles or casks, which is negotiated separately. A fruit farm with compliant premises and a name known locally is worth well beyond its plantings.
The outlet shows up in the seller's order book: producers' shops, markets, grocers, restaurants, pick-your-own, sometimes a liqueur house or a cooperative. Ask what share each channel takes and how steady the volumes are from one season to the next. Seasonal labour deserves the same attention: the cherry harvest is short and demanding, the local workforce limited, and accommodation for the crews rarely provided. A holding that has kept its pickers coming back hands over an asset that appears on no deed.
Start with the status of the parcels. Fragmentation is the rule here, with blocks spread over several separate plots, sometimes landlocked or served by private tracks: have the accesses, the easements and the boundaries checked before making an offer. Part of the land is rented, and the rural lease continues with the buyer subject to the landlord's agreement; the deal goes through the structures control, the French authorisation regime for taking over farmland, and remains exposed to SAFER's pre-emption right. The spray register, the no-treatment zones beside dwellings and the chemical store also need checking.
Then work out the real cost of bringing the orchard back into production: grubbing, soil analysis, replanting, protection against deer and the seasons without income before a genuine first crop. That item is decisive on the ageing orchards which are common in this region. If the blocks are certified organic, the certification transfers with whatever conversion period is still running. Finally, for a setting-up project, make sure the agricultural professional qualification is held before signature and that the grants applied for fit the seller's own timetable.
This page fills up as businesses change hands: properties entrusted directly by growers, mandates held by rural property specialists, files opened in notaries' offices. Pick a department, a range of areas or a budget, switch on an e-mail alert so you do not miss an apple orchard or a small processing unit coming to market, and carry on through the farms for sale in Bourgogne-Franche-Comté.